Day-Ahead and Real-Time Price Trends by Components and by Zone
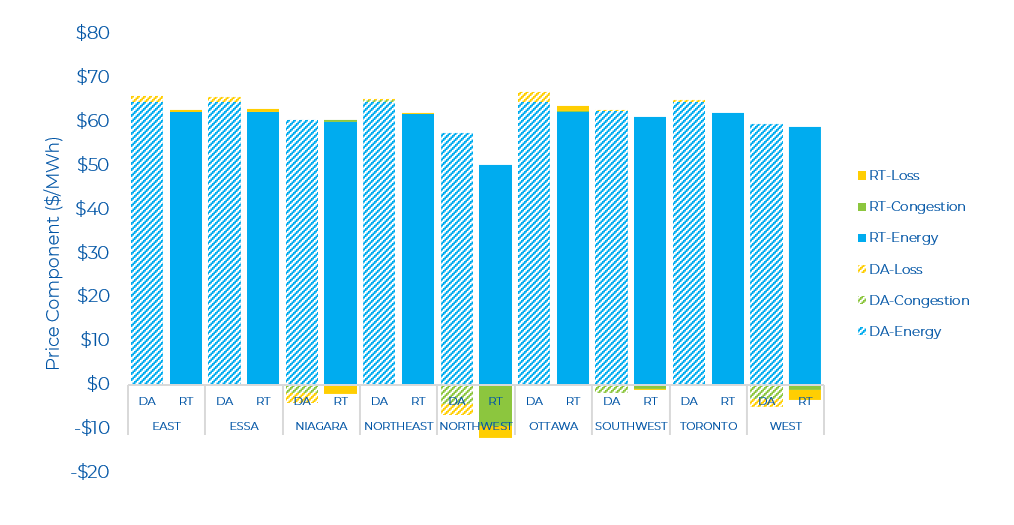
Ontario’s wholesale market in August posted lower prices across all zones in the day-ahead market compared to real-time. Similar to previous months, the Northwest zone showed the lowest prices, while the Ottawa zone showed the highest prices. DA zonal prices ranged from $58/MWh (Northwest) to $67/MWh (Ottawa), while Real-Time (RT) zonal prices ranged from $50/MWh (Northwest) to $64/MWh (Ottawa).
The DA and RT price by zone and by component for August is shown below. Prices in the Northern zones and Ottawa zone were mainly impacted by congestion due to reduced capacity on major transmission interfaces – highlighting well known constraints that appeared in the renewed market since it was launched in May 2025.
Day-Ahead and Real-Time Prices
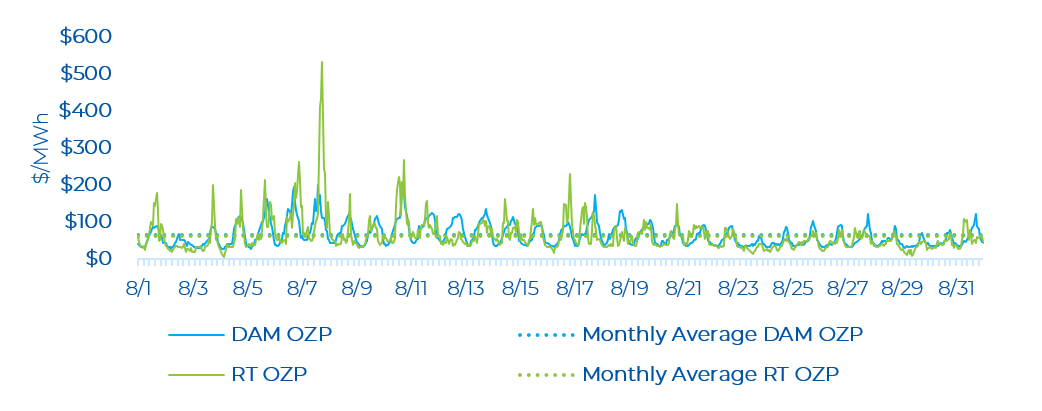
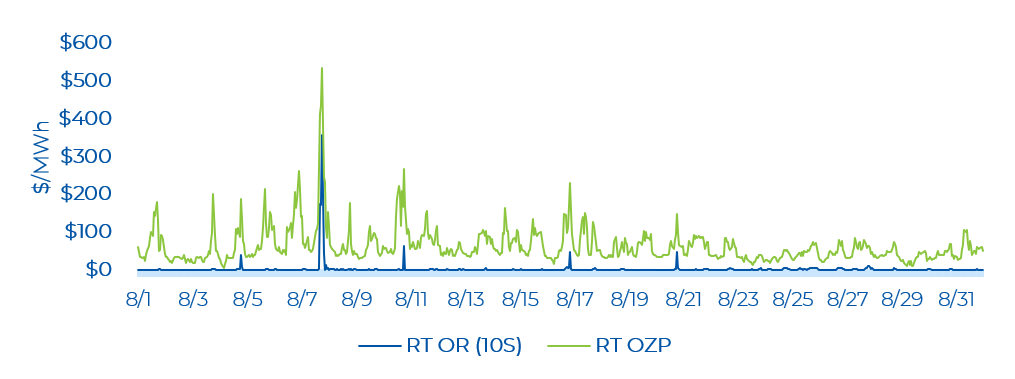
August saw more moderate demand and prices compared to July. The peak demand in August was 23,142 MW (on August 10, HE 17) – 2,504 MW lower than the record-breaking peak in July. The highest real-time OZP was $532.09/MWh (on August 7, HE 19). Ontario demand when OZP hit its highest level – was 22,344 MW. Compared to July, August had less frequent prices above $200/MWh and a lower monthly average price. There were 15 real-time hourly OZP spikes greater than $200/MWh. The average hourly day-ahead OZP was $63.88/MWh in August, while the real-time OZP was $61.52/MWh. In contrast to August 2025, Ontario demand last month was lower but average monthly energy prices were higher by about $0.51/MWh to $7.56/MWh in the day-ahead and real-time market. The higher energy prices experienced this August were likely driven by the three Darlington nuclear units that were offline, forcing increased gas generation to make up the difference.
OR Prices
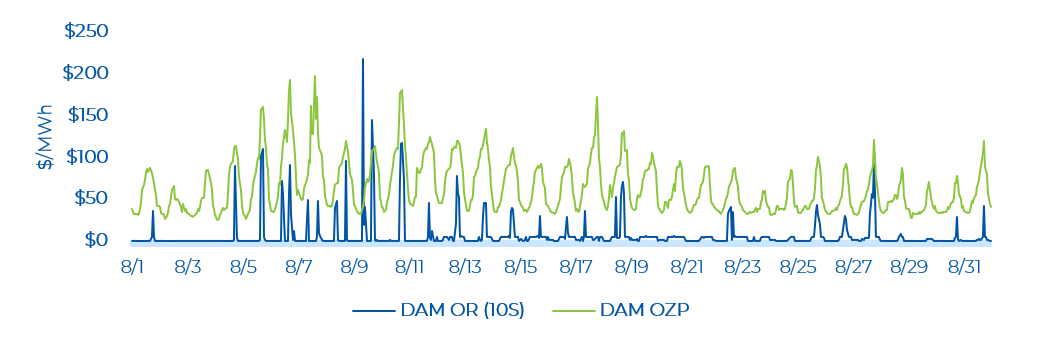
Low day-ahead and real-time average monthly OR prices were similar to what was observed in July. The average monthly day-ahead 10S price was $6.11/MW, while it was $1.74/MW in real-time. The highest real-time OR price spike was $356.12/MW. In the day-ahead market, the most common 10S price was $0.10/MWh (occurred 37% of the time). In the real-time market, the most common 10S price was $0.09/MWh (occurred 17% of the time). The low OR prices from July continued in August. Overall, there has been a continued downward trend in OR prices since the renewed market was launched – at least partly explained by the increase in energy storage coming online over the past year.
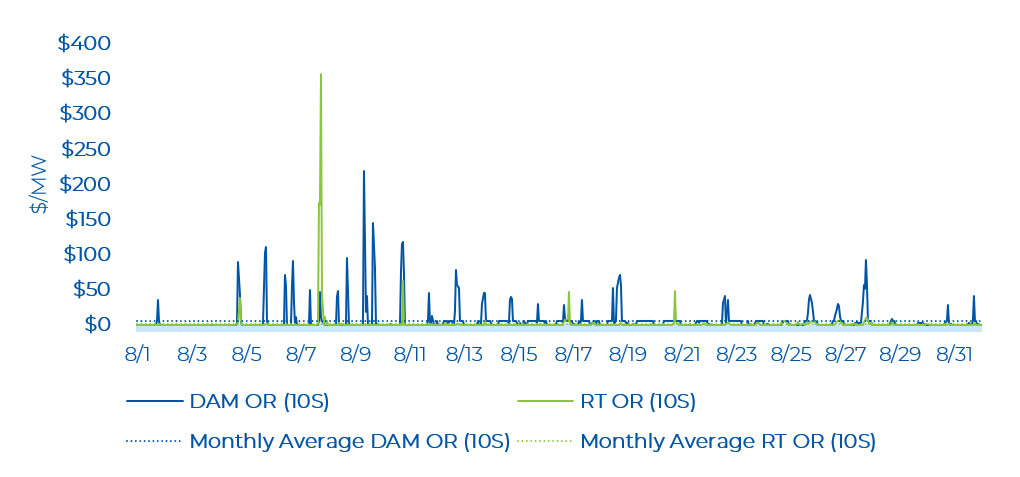
The highest day-ahead OR price was $218.20/MW, which occurred on August 9, HE 9. The day-ahead energy price was $41.16/MW at this time. The day-ahead OR price exceeded the day-ahead energy price in only two hours in August. This is similar to July, where zero hours experienced the OR price exceeding the energy price.
Real-time OR prices were low (i.e., near $0.09/MW) for many hours. There were some hours with real-time OR price spikes, coincident with real time OZP spikes. The highest real-time OR price was $356.13/MW on August 7, HE 19. The real-time OR prices did not exceed the real-time energy prices.
Zonal Prices and Congestion
The average real-time nodal price (LMP) across Ontario for August is shown in the figure below. Similar to July, all nodes across Ontario had fairly elevated prices compared to shoulder months. In contrast to July, there was less divergence between LMPs in the northern zone vs other zones in the rest of Ontario.
Map 1: Average IESO Nodal RT LMPs ($/MWh) for August
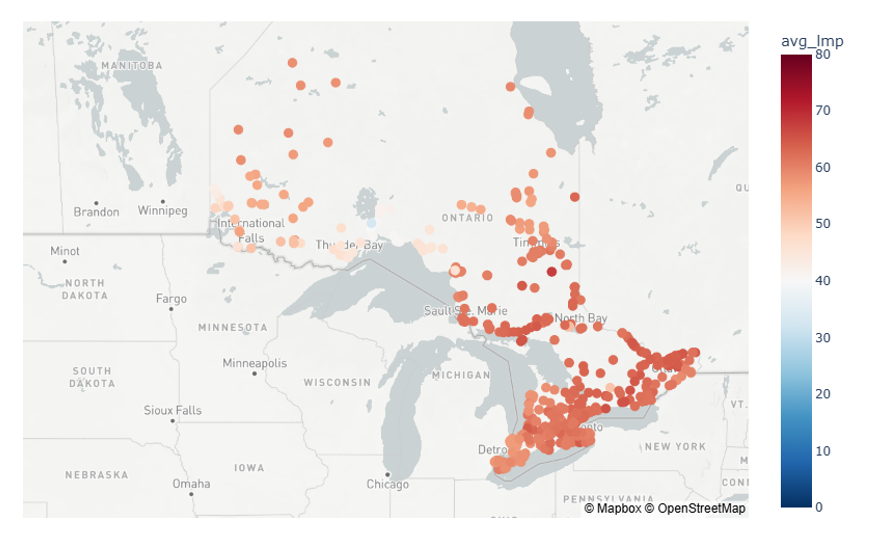
Similar to July, in August the prices across nodes in the Northwest zone were much lower than other zones.
Map 2: Lowest Observed IESO Nodal RT LMPs ($/MWh) for August
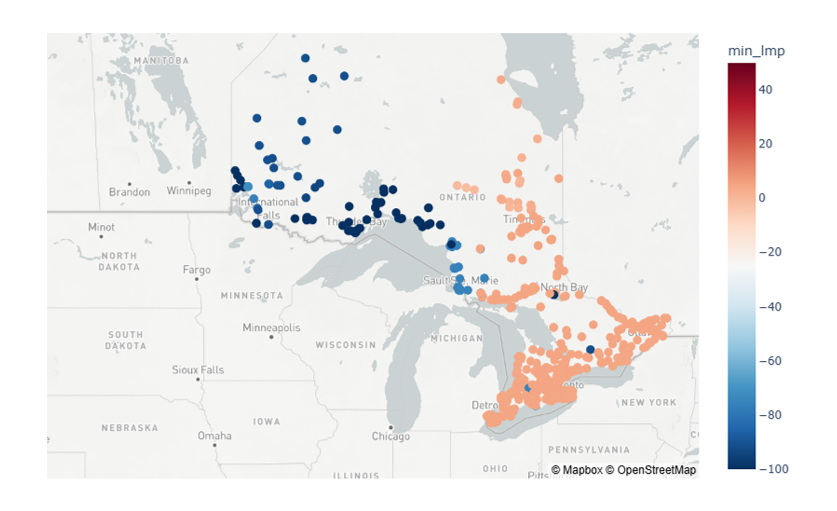
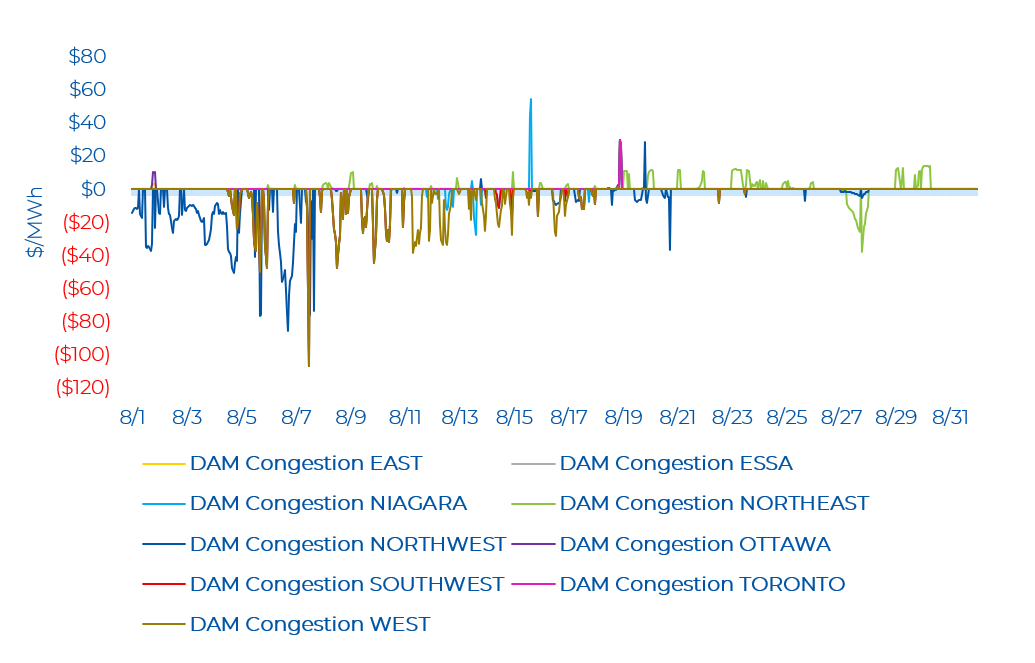
In contrast to July, August showed lower congestion across several zones in the day-ahead market. The Northwest zone saw a high of $29.47/MWh and a low of -$85.74/MWh. The Northeast zone saw a high of $29.47/MWh and a low of -$37.93/MWh. Congestion in the East and Ottawa zones was minimal and occurred mostly at the same hours. The Niagara, Southwest, and West zones mainly had similar negative congestion in the same hours. All three zones experienced a low of -$106.71/MWh (on August 7, HE 12). Note that negative congestion typically means there was a constraint exporting energy from a particular zone (and lower energy prices), while positive congestion is the opposite.
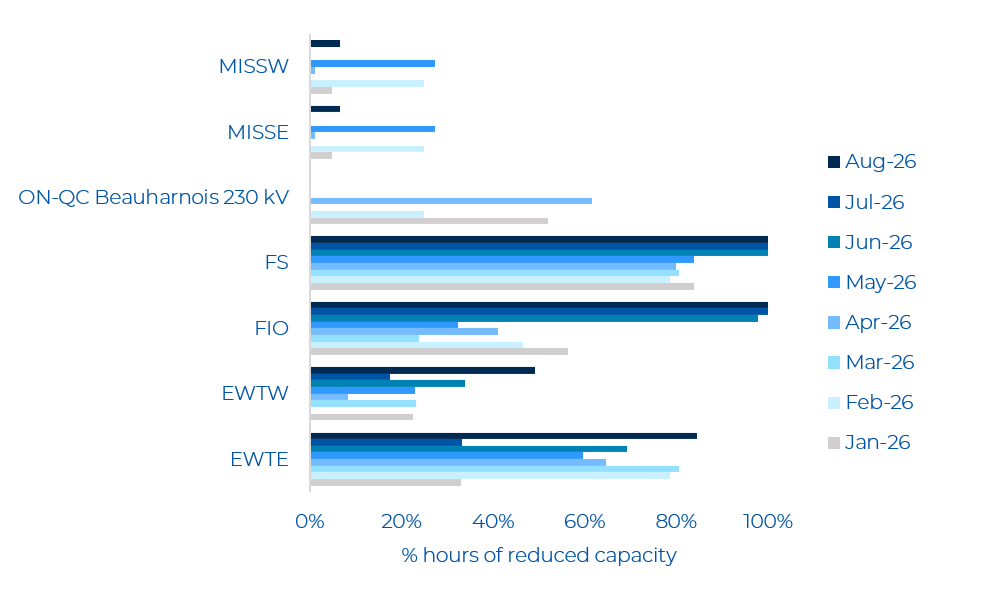
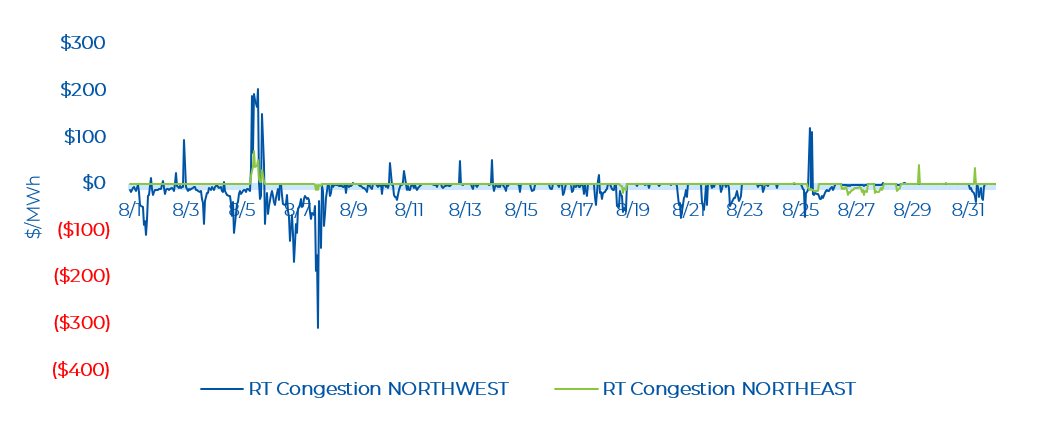
In real-time, the Northwest and Northeast zones saw several hours of negative congestion in August, but the severity of the congestion was less extreme than July. The Northwest zone saw a high of $203.08/MWh in congestion and a low of - $309.95/MWh. The Northeast zone saw a high of $70.13/MWh and a low of - $24.58/MWh. A concentration of positive congestion observed in these zones occurred on August 5 which was one of the higher demand days in the month. For several hours in August, there were outages on the East-West Transfer East (EWTE)/East-West Transfer West (EWTW) and Flow Into Ottawa (FIO) interfaces. Flow-South (FS) continued to operate at minimum capacity for August. In contrast to July, there were fewer occurrences of reduced capacity on the Northern interfaces impacting the relatively lower congestion observed in these zones.
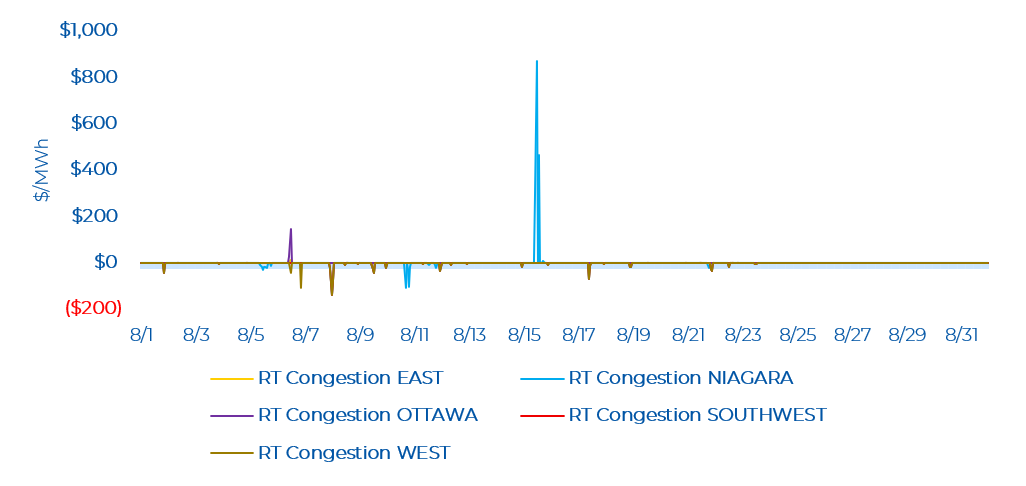
Other than the Northern zones, in real time, there was a high positive spike in congestion in the Niagara zone on August 15, HE 12. At this hour, Ontario demand increased by more than 400 MW. The Ottawa zone observed one spike above $100/MWh. There were a couple hours of negative congestion in the Southwest and West Zones both with a low of -$141.27/MWh (as well as with the Niagara zone). The Essa zone had minor congestion.
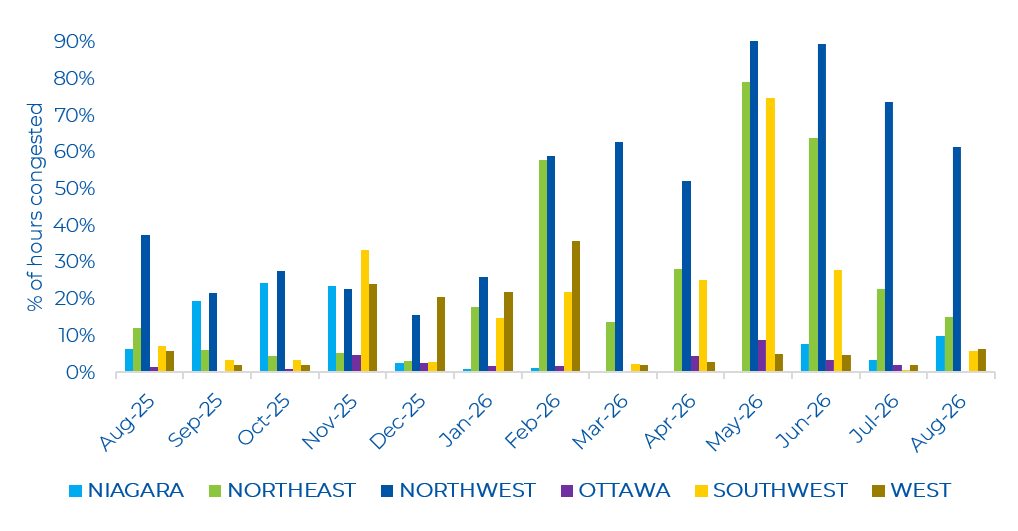
Similar to July, the Northern zones show frequent hours of congestion (but at a lower magnitude). Compared to August of last year, there was also more congestion in the northern zones. From July, the number of congested hours in the Southwest, West, and Niagara zones have increased. Congestion in the Ottawa zone is minor.
As shown in the figure below, August saw more reduced capacity on EWTE/EWTW interfaces compared to July. Compared to July, there were similar levels of reduced capacity on the FS and FIO interfaces.